UK Business News Today: 3 November 2026 | Economy, Markets & Insolvencies
A busier order book is welcome, but it does not automatically mean more cash in the bank. UK manufacturing is growing faster while input costs keep climbing, households face another mortgage squeeze, and Poundland’s suppliers are warning about the consequences of a potential administration.
There is a more encouraging prospect in the draft UK–EU food trade deal, which could cut paperwork and border costs. For businesses selling on credit, today’s priority is to distinguish customers with a credible growth story from those struggling to fund the next payment.
James Salmon, Operations Director.
Key Developments
- UK manufacturing PMI rises to 52.8, but persistent input-cost inflation threatens margins.
- A possible Bank Rate rise to 4% on Thursday adds to concerns about mortgages, consumer spending and business finance.
- Draft UK–EU food trade arrangements could remove costly certificates and checks, subject to final agreement and implementation.
- Poundland’s supplier dispute highlights the exposure created by dependence on a large customer.
- Oil rebounds and technology shares weaken; today’s supplied notices cover 29 unique companies.
Economy & Policy
Manufacturing grows, but the cost squeeze continues
October’s UK manufacturing PMI rose to 52.8 from 51.9 in September, a five-month high and above the 50 threshold separating growth from contraction. The outlook improved to its strongest in eight months. However, the supplied S&P Global report says input costs have risen for 34 consecutive months, with cost inflation at a four-year high. RSM UK economist Thomas Pugh expects inflation to approach 5% in the new year and argues that higher interest rates are needed to limit the spread of price pressures.
Why it matters: Rising sales can still consume working capital when materials must be paid for before customers settle their invoices.
Mortgage competition offers limited shelter from higher rates
Bank Rate remains at 3.75%, with the next decision due on Thursday 5 November; the supplied reports anticipate a rise to 4%, rather than a decision already taken. Banks are competing for remortgage business as 2.3 million households approach the end of fixed-rate deals, putting pressure on lenders’ margins. Connells estimates that higher mortgage rates have caused 100,000 buyers to postpone purchases this year, with average rates rising from 4.14% in January to 5.22% in October. Its illustrative monthly repayment on a typical 75% loan-to-value mortgage rises from £1,115 in the earlier comparison period to £1,224; Connells expects some delayed buyers to return next year if rates ease. the UK’s central bank
Why it matters: Higher household repayments can reduce discretionary spending, while delayed moves affect estate agents, trades, furniture suppliers and their creditors.
Short sellers increase their exposure to housebuilders
White & Case reports that the number of companies with more than 5% of their shares held short more than doubled to 60 in three months. The supplied figures put Vistry at 16.7% and Ibstock at 12.9%, against a backdrop of material-cost pressures and weaker margins. Short positions reflect investors betting on share-price falls; they are a market signal, rather than evidence that a company is insolvent.
Tax & Government
HMRC clarifies criminal penalties for avoidance promoters
HMRC’s prohibition on promoting certain tax avoidance arrangements took effect on 19 May 2026. It covers arrangements marketed as offering a tax advantage with no realistic prospect of achieving it, as well as categories specified under the legislation. Breaches can lead to criminal fines and up to two years’ imprisonment; HMRC also sets out civil penalties of up to £1 million plus £5,000 per participant. The guidance distinguishes the targeted conduct from legitimate advisers making good-faith mistakes. GOV.UK
Finance bodies press for a clearer digital asset strategy
Nearly a dozen industry bodies have urged Chancellor John Healey to accelerate a central strategy for cryptocurrencies and digital assets. According to the supplied report, the Financial Services and Markets Bill envisages a strategy within 12 months, but the organisations fear that commitment could be diluted. Their concern is that uncertainty will weaken the UK’s competitiveness and deter investment.
Employment & Labour
Workers want more flexibility, with fewer favouring full-time roles
Resolution Foundation analysis of the British Social Attitudes Survey shows that the share of working-age adults ideally wanting full-time work fell from 57% in 2015 to 47% in 2025. The fall was concentrated among men, whose preference declined by 15 percentage points; the supplied report also puts male job satisfaction down from 79% to 70%. This does not mean most people want to stop working: the survey’s publisher says only 4% of working-age adults would ideally prefer no work at all. National Centre for Social Research
Collective pensions aim for lifetime income, with variable payments
Ministers want to expand collective defined contribution pensions, which pool savings and share investment and longevity risks. These arrangements aim to provide an income for life and potentially better average outcomes, but the amount paid is not guaranteed and can rise or fall. They should therefore not be described as guaranteed inflation-proof pensions equivalent to public-sector defined benefit schemes. Further auto-enrolment reforms are expected next year in the supplied report, with details still to come. GOV.UK
Settlement reforms reshape the recruitment outlook
The Home Secretary has announced a settlement framework with a ten-year default and shorter routes for specified groups. The supplied report puts the three-year route at earnings above £125,140, with eligible entrepreneurs and global talent applicants also covered; a five-year route is envisaged for higher earners and qualifying public-sector workers. Qualifying care workers earning at least £25,000 can retain a five-year path, while some others would receive a further five-year visa allowing a change of employer. The plans are intended to affect people already in the UK, but implementation is phased and the supplied reporting says the three-year route is unlikely to start in 2026. GOV.UK
Retail & Consumer
Poundland supplier appeals over potential administration
BMI Limited, associated with pet-food brands including Vitagen and Husky, has urged ministers to intervene over Poundland’s possible administration. Ravi Madan of BM International has written to Business Secretary Jonathan Reynolds, raising concerns about how insolvency procedures could affect suppliers. Those concerns are the supplier’s allegations and do not establish wrongdoing or confirm that an administration has occurred.
Why it matters: A major customer can account for a dangerous share of unpaid invoices: review total exposure, overdue balances and whether further deliveries increase the potential loss.
Consumer brands report a cautious shopper
Primark’s like-for-like sales fell 2.5% in the six months to 12 September, according to the supplied market recap, with European customers particularly cautious. Hugo Boss cut full-year operating profit guidance to €250 million–€300 million from up to €350 million, citing demand weakness and higher technology costs. Together, the updates suggest that discretionary spending remains under pressure even where individual businesses continue to grow.
Oxford Street’s transformation offers opportunity, with limits
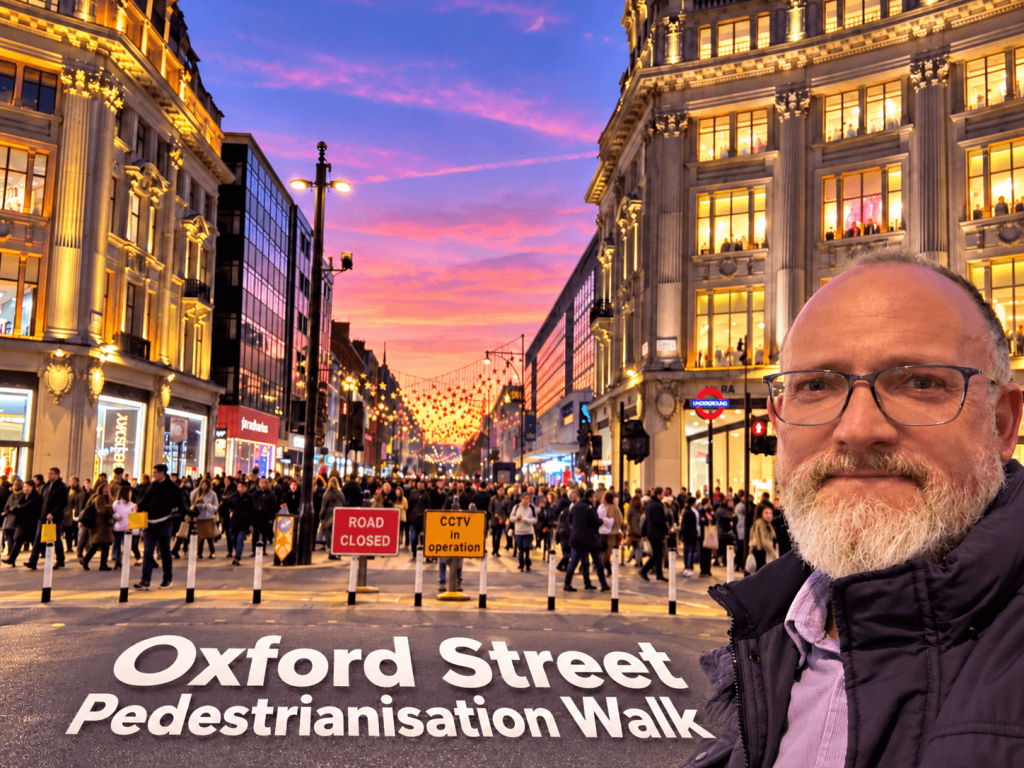
As I personally experienced on the weekend, a one-kilometre stretch of Oxford Street has become permanently vehicle-free, with further public-space improvements planned. It is a retail area attracting 120 million visits a year, yet its November 2024 footfall was only 57% of the 2006 level, behind neighbouring Regent Street and Bond Street. The project demonstrates how coordinated planning can help an established retail destination, while its tourist profile and transport links limit comparisons with smaller high streets.
International & Trade
Draft UK–EU food deal could cut border costs
A 200-page draft agreement on food, animal and plant trade has been circulated ahead of the 20 November UK–EU summit. The proposed arrangements could remove the need for £200 Export Health Certificates, £25 phytosanitary certificates and a range of other checks and fees, while reopening access for some currently restricted products. In return, the UK would align relevant rules with the EU as those rules change, with substantial implications for food businesses and movements to Northern Ireland. Government preparation guidance targets mid-2027, subject to negotiations: the draft does not remove today’s requirements, while the projected economic benefit of up to £5.1 billion annually is a longer-term estimate for 2040. GOV.UK
Why it matters: Lower border costs and shorter delays could reduce the cash tied up in food shipments and make smaller export orders more viable.
Wider EU reset remains under negotiation
The proposed package also covers emissions trading, economic security, supply chains, police cooperation and a youth travel and work scheme. Linking emissions systems is intended to reduce carbon-border friction, while the UK wants reassurance over access to European procurement under proposed Made in Europe measures.
Energy & Costs
Oil rebound and expensive power renew pressure on margins
Brent and WTI have rebounded after Monday’s sharp oil-price fall, as a US strike on Iran’s Qeshm Island tempered optimism about diplomatic progress. Cold weather is also increasing Europe’s reliance on coal and gas generation, with electricity prices at levels last seen during the 2022 energy crisis. European gas futures rose as much as 3.9%, while Lufthansa flagged a €543 million increase in third-quarter fuel costs. US proposals to ease methane requirements aim to lower producers’ costs, but do not resolve immediate price and supply volatility.
Why it matters: Transport, refrigeration, manufacturing and other energy-intensive businesses need to revisit margins and cash forecasts when costs move faster than customer prices.
Industry & Investment
AI spending grows faster than confidence in the returns
Anthropic’s pre-IPO filing reportedly discloses $895 billion of computing and infrastructure commitments. Quarterly revenue rose to almost $17 billion from $1.4 billion a year earlier, yet the company reported a $567 million operating loss after a $974 million operating profit in the previous quarter. Separately, the supplied recap reports £2.5 billion of Brookfield and QIA investment in a Drax data-centre project, targeting an initial 100MW phase by the first quarter of 2028. These developments illustrate both the commercial opportunity and the substantial capital needed to support it.
Marvell’s proposed Lumentum acquisition meets investor resistance
Marvell has agreed an all-stock acquisition of Lumentum with an announced implied enterprise value of $115 billion. The companies say it would combine semiconductor design and optical connectivity for AI data centres; completion remains subject to approvals. The later supplied report puts Lumentum’s share-price fall above 18% and Marvell’s at almost 13%, highlighting investor concern about the terms and sector valuations.
Apple and Palantir show growth, with different pressures
Apple reported quarterly revenue of $114.5 billion, up 12%, and diluted earnings per share of $2.10 in its first results under John Ternus. Gross margin reached 47.9%, including roughly one percentage point from tariff refunds. December-quarter revenue growth guidance is 7%–10% and a lower margin of 45%–46% as memory costs rise. Palantir reported revenue of about $2.3 billion, up 96%, with its US commercial revenue exceeding US government revenue for the first time. Both demonstrate demand for technology, while Apple’s outlook shows that strong sales do not eliminate component-cost pressures. Apple
An extraordinary journey reaches Hull
Karl Bushby has reached Hull after the 28-year journey that began in Chile in 1998, according to the supplied report. His route took him through the Americas, across the Bering Strait and through Eurasia, with setbacks including detention in Russia. It is an unusual reminder that long-term plans require both persistence and the ability to adapt when the original timetable proves unrealistic.
Global Market Summary
Equities: energy and technology concerns reverse Europe’s gains
European shares opened lower after Monday’s advance, as renewed energy inflation concerns combined with the semiconductor sell-off and caution ahead of the US midterm elections. Monday’s FTSE 100 gain of 0.30% and STOXX Europe 600 rise of 0.40% had followed a sharp drop in oil prices; Tuesday’s rebound in crude reversed some of that relief. In the US, the Dow rose while the S&P 500 and technology indices fell, illustrating the uneven impact across sectors.
| Index | Level | Move | Session |
|---|
| FTSE 100 | 10,704.98 | −0.52% | Tuesday morning |
| STOXX Europe 600 | 645.77 | −0.57% | Tuesday morning |
| Euro STOXX 50 | 6,122.25 | −0.87% | Tuesday morning |
| DAX | 25,752.98 | −0.88% | Tuesday morning |
| CAC 40 | 8,008.92 | −0.48% | Tuesday morning |
| S&P 500 | 7,541.40 | −0.51% | Monday close |
| Dow Jones | 51,983.98 | +0.41% | Monday close |
| Nasdaq Composite | 25,164.36 | −1.07% | Monday close |
| Nikkei 225 | 63,081.86 | −0.33% | Monday close; Tuesday holiday |
| Hang Seng | 23,525.97 | +0.57% | Tuesday supplied close |
The separate Nasdaq 100 closed at 27,989.82, down 1.4% in the supplied update and around 10% below its peak. The Philadelphia Semiconductor Index fell 3.4%; weakness carried into Asian and European chipmakers. South Korea’s Kospi dropped 3.59%, while Hong Kong outperformed as mainland buying increased. Australia’s ASX 200 gained 0.34%, and Chinese support measures struggled to restore confidence on the mainland.
Corporate results provided pockets of support: Bayer raised profit guidance, Philips improved margins and Lufthansa beat quarterly expectations. Alstom’s outlook cut weighed on its shares, while BP’s completed Castrol stake sale generated $6 billion of after-tax proceeds. The market backdrop therefore combines growth opportunities with clear differences in balance-sheet strength, costs and demand.
Currencies: sterling edges higher
| Pair | Rate | Daily move |
|---|
| GBP/USD | 1.3414 | +0.06% |
| GBP/EUR | 1.1991 | +0.06% |
Sterling’s modest advance is associated with expectations of tighter Bank of England policy, while the dollar index was almost unchanged at 101.74 ahead of major US events. A stronger pound can ease the sterling cost of foreign-currency purchases, but makes UK exports more expensive for overseas customers if sterling prices stay fixed.
Commodities: energy rises, metals retreat
| Commodity | Price | Daily move |
|---|
| Brent crude | $106.46 per barrel | +1.58% |
| WTI crude | $97.89 per barrel | +1.48% |
| Gold | $3,899.77 per ounce | −1.18% |
Oil’s rebound reflects doubts about how quickly US–Iran diplomacy can ease the conflict and protect supply routes. European gas rose as much as 3.9%, while the separate US natural-gas contract was $2.904 per million British thermal units, up 1.68%; those are different markets.
Silver fell 3.78%, and copper dropped below $14,000 a tonne on the London Metal Exchange as concerns about AI investment clouded demand. Gold’s pullback came despite strong recent central-bank buying, with the supplied World Gold Council figures showing net purchases of 321 tonnes in the third quarter.
Rates and the events to watch
ECB policymakers warned that their pause need not mark the end of tightening. US Treasury yields remained elevated at 4.59% for two years, 4.91% for ten years and 5.29% for thirty years, helping keep global financing conditions demanding.
Investors are watching the US midterms, Tuesday’s job-openings and factory-orders releases, Wednesday’s Treasury borrowing announcement and Friday’s employment report.
Insolvency Watch
Administrations (8)
- CHAMELEON TECHNOLOGY (UK) LIMITED
- FELIX RESTAURANTS (WARLEY) LTD
- L.CAMERON & SON LIMITED
- NEWHAVEN PHARMACIES LIMITED
- PREDDY NEWCO LIMITED
- QUANTA EPC LIMITED
- REBORNE LONGEVITY LTD
- YHANGRY LTD
Liquidations (17)
- AP ASSOCIATES (CRANLEIGH) LIMITED
- BMH SERVICES LIMITED
- CEVIAN55 LTD
- CONSTANTIA ESTATES LIMITED
- CSK PETROLEUM CONSULTANTS LIMITED
- CUBA CONSULTANTS LTD
- DASHWOOD ESTATES LIMITED
- DELE ALLI PROMOTIONS LTD
- DENNIS WILLIAMS LIMITED
- INDIGO GOLD LTD
- L.B.S. (FORT WILLIAM) LIMITED
- NTECK SOLUTIONS LIMITED
- PIMPERNE PROJECTS LTD
- RANGETEN LIMITED
- WHARFE PROPERTIES LIMITED
- YOU ARE THE DIFFERENCE LIMITED
- ZUVION LIMITED
Winding-up Petitions (4)
- EYRE HOSPITALITY LTD
- H & N DEVELOPMENTS LLP
- MINIBEMS LIMITED
- THE GREYHOUND HAVERSHAM LTD
Keeping growth from becoming a cashflow squeeze
Today’s stories share a practical lesson: stronger demand does not remove the need to fund materials, wages and energy while waiting to be paid. Review the customers taking the largest share of your available credit, keep an eye on changing payment patterns and follow up overdue invoices promptly and professionally.
CPA’s CreditCare credit reports and debtor monitoring can help you assess customers and review exposure as conditions change. Credit control support and overdue account recovery can help improve payment performance while preserving customer relationships.
Call CPA on 020 8846 0000 during business hours, Monday to Friday, 9am to 5pm.
Email PaidQuick@cpa.co.uk.
Visit https://cpa.co.uk/contact-us/.
When you see your money come in, you will be so glad you used CPA.
The Credit Protection Association : Prompting Punctual Payments : Ethical, Effective, Efficient, Economical collections.
Open this guide in a new tab
.